This article will take approximately 20 minutes to read. Don't have the time right now? No worries. Email the ad-free version of the article to yourself and read it later!
When I first arrived in Japan, it was an overwhelming experience. I had prepared a checklist of tasks to complete after meeting my supervisor at the airport, but I was unprepared for the language barrier and the intricacies of settling in. Remember, this was 15 years ago, and today, life has become much more convenient for foreigners residing here.
I’ve put together a comprehensive guide on an essential aspect of settling in Japan: opening a bank account. While it isn’t rocket science and doesn’t demand any specific skills, I hope this guide smoothens your experience. I’ll also share some insider tips to make the process hassle-free.
Contents
- Key Takeaways
- Good to Know
- Which Bank to Choose?
- The Six-Month Rule, and How to Get Around It
- Required Paperwork
- Do You Still Need a Hanko?
- Initial Deposit
- Basic Conversation for Opening a Bank Account in Japan
- Waiting for Approval
- ATM Card and Tsuuchou
- What You Can Do with Your Account
- Mobile Banking Options
- Maintenance Fees
- What a Japanese Account Will Not Do Well
- Banking Hours
- Withdrawing Money with a Foreign Card in Japan
- Now, on to You
- Frequently Asked Questions
- Sources Cited
Key Takeaways
- Japan Post Bank, SBI Shinsei Bank, and Sony Bank are the most expat-friendly options, all offering English-language services and online account opening.
- You need your Residence Card, passport, proof of address, a Japanese phone number, and usually a hanko (personal seal) to open an account.
- Expect to wait 1-2 hours at the branch; calling ahead to notify them of your visit helps speed up the process.
- There are no maintenance fees for standard Japanese bank accounts, and salaries are typically paid once a month directly to your account.
- Banks close for Golden Week (late April to early May), Obon (mid-August), and New Year holidays, so plan bill payments and withdrawals around those closures.
- Wise is widely used by expats for international transfers as it avoids SWIFT fees and offers near-interbank exchange rates.
Good to Know
While Japan’s banking system is as robust and efficient as those in other developed nations, it can appear confusing to newcomers due to linguistic challenges and cultural intricacies.
Japan has an eclectic mix of megabanks, digital banks, and regional banks.
City banks, often referred to as ‘megabanks’, are prevalent in major urban areas with numerous branches and ATMs.
Regional banks, as the name indicates, are location-specific, usually at the prefectural level. Your employer might have a tie-up with a regional bank and may suggest you open an account there, but remember, this is entirely optional.
Which Bank to Choose?
Choosing the right bank is crucial, but remember you can open multiple accounts. If you’re unsatisfied with your bank’s service, it’s relatively easy to switch. The following banks offer services in English and cater well to international customers.
Tip: If you work in Japan, you might not have an option to choose. Check with your employer to see if they have a preferred bank for direct deposits.
Here’s a brief guide:
Japan Post Bank

It’s among Japan’s largest banks with widespread branches and ATMs. A highlight is its dual function as a post office.
You can complete banking and shipping tasks under one roof. The bank also lets you fill out an account application online, which can be printed and presented in-person.
SBI Shinsei Bank

Shinsei Bank rebranded to SBI Shinsei Bank in January 2023 after SBI Holdings acquired a majority stake. Known for English services and extensive mobile banking. Interestingly, a personal seal isn’t needed to open an account.
But be prepared for a bit of a learning curve with their mobile platform due to the complexity of Japanese web design.
Sony Bank

It’s primarily an online bank with English services.
The account opening process is straightforward. The downside is the lack of physical branches, which might be inconvenient if you encounter issues with your account.
Other
Other banks like SMBC Trust Bank, Mitsubishi UFJ Bank, Mizuho Bank, and Seven Bank (7-11 bank) also have English support.
Of these, 7-11 stands out for its ATM convenience, allowing withdrawals from any 7-11 across Japan without fees.
The Six-Month Rule, and How to Get Around It
This is the wall most new arrivals hit. Many Japanese banks will not open an account for a foreign resident who has been in the country less than six months, and nobody warns you before you land.
Understanding why helps you work out which door to knock on. The rule comes from anti-money-laundering practice rather than from a single statute, and banks apply it with their own discretion, which is exactly why it is inconsistent between branches of the same bank.
The practical ways around it, roughly in order of how often they work:
- Japan Post Bank. The usual answer for someone freshly arrived, because it is the most likely to open an account before the six months are up.
- Your employer’s letter. A written statement from the company confirming your employment, often naming the branch where your salary will be paid, carries real weight. Ask HR before you go.
- The branch your employer or university already uses. Institutions have working relationships with specific branches, and a branch that regularly onboards that employer’s foreign staff is far less hesitant.
- Online-first banks. Several operate with lighter branch friction, though they have their own requirements and are not a guaranteed shortcut.
If you are refused, do not assume it applies everywhere. A different branch of the same bank, on a different day, with an employer’s letter in hand, is a genuinely different conversation. Confirm the current position with the bank rather than trusting what a forum said last year.
Required Paperwork
To open a bank account in Japan, most banks require a combination of, if not all, the essential paperwork listed below:
- your Residence Card (Zairyu Card)
- your passport
- proof of address
- a hanko/inkan (personal seal/stamp with your full name on it. You can visit any hanko shop and get it)
- and something that often posed a significant challenge for newly arriving foreigners: a registered Japanese mobile number.
Additionally, gather your employment or student information as a precautionary measure. This can be a written statement from your company or a student ID card if you’re enrolled in a college/university.
Some banks make students wait longer than six months, depending on the bank.
Consult the bank’s website for detailed instructions on required documents as there might be slight differences between banks.
Residence Card (Zairyu Card)
It serves as proof of your residential status in Japan and displays your visa expiration date. Japanese banks mark the expiration date of your residential status in their systems.
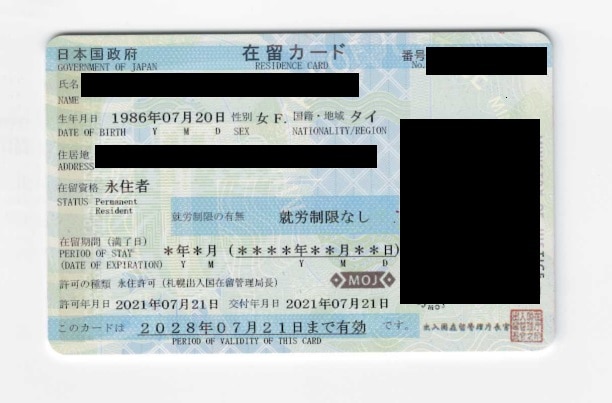
They might ask for a minor paperwork update (usually visiting the bank with your renewed visa card) to continue serving you. This wasn’t always the case; the update was introduced to combat money laundering. You can obtain your residence card from the immigration office.
Sometimes, your new Japanese employer will gather your personal details and photo in advance, preparing and registering the card for you prior to your arrival.
Remember, this card is crucial for most activities in Japan. There’s also a “My Number” card, a tax ID card with insurance details. However, applying for this card is optional, with many Japanese citizens forgoing it.
Passport
Ensure your passport is renewed before coming to Japan. An expiring passport while you’re in the country can lead to inconvenience.
Proof of Address
A document such as a “jumin-hyo” from your local municipal office or a utility bill will suffice. If your employer or educational institution is providing accommodation, they can also provide proof of residence.
Hanko/Inkan
This personal seal with your name written in katakana is often used in place of handwritten signatures on formal documents. They can be bought from specialized stores. If your name isn’t common in Japan, you’ll need to visit a store that provides engraving services. While there are hanko vending machines available, they’re less common nowadays.
Japanese Phone Number
This is essential for bank communication. You can get a local number from telecom companies like Softbank, NTT Docomo, or AU. Many foreigners opt for a temporary solution like a prepaid SIM card or a virtual phone number from providers like Mobal, Callhippo, Krispcall, and Didww.
Note that tourists can’t legally obtain a phone number that allows voice calls in Japan. Since you won’t be on a tourist visa, this won’t be a concern. Many newcomers secure a virtual number before arriving in Japan, but these might not always be accepted for service verification. Research and pick a solution that suits your needs.
Do You Still Need a Hanko?
Less than you used to, and this is an area where Japan has genuinely moved. A personal seal was once non-negotiable for banking. Now a signature is accepted in plenty of places, and some banks state outright that no seal is needed to open an account.
Where it still catches people out:
- Policy varies by bank and sometimes by branch, so ask the branch you are going to before you go.
- A seal is often still wanted beyond banking, including for rental contracts and some employment paperwork, so many residents end up getting one anyway.
- If you do get one, a non-Japanese name is normally rendered in katakana, and cheap ready-made seals will not carry your name, so it is an order rather than something you pick off a shelf.
- Once a seal is registered to an account, use the same one consistently. A seal that does not match the registered impression means a rejected form.
The practical approach: do not buy one before you arrive. Ask your bank and your landlord what they need, then get one made locally if the answer is yes.
Initial Deposit
Be aware that some banks may require a minimum deposit to initiate an account. The amount varies; some banks may ask for as little as 1,000 yen, while others might have no such requirement.
Basic Conversation for Opening a Bank Account in Japan
Here’s a basic conversation that could occur when opening a bank account in Japan.
Please understand that this is a simplified example, and actual interactions might vary. If you are outside major cities like Tokyo, finding an English-speaking bank representative might be rare. So, it’s best to learn Japanese while living in Japan.
Customer: Sumimasen, ginkō koza o hirakitai desu. (Excuse me, I want to open a bank account.)
Bank Teller: Hai, wakarimashita. Hitsuyōna shōmei-sho wa motte imasu ka? (Yes, understood. Do you have the necessary documents?)
Customer: Hai, pasupōto, zairyū kādo, jūsho shōmei, denwa bangō, hanko, shokugyō jōtai, koza mōshikomisho, wo mottekimashita. (Yes, I’ve brought my passport, residence card, proof of address, local phone number, personal seal, employment status, account application form, deposit money, ATM card, and PIN number.)
Bank Teller: Mōshikomi-sho ni hitsuyōna jōhō o kinyū shite kudasai. (Please fill in the required information on the application form.) *It’s advisable to have filled this out online beforehand if possible.
Bank Teller: Donna kouza wo hirakitai desu ka? Futsuu yokin ka, tosho yokin ka? (Which type of account would you like to open? A regular savings account or a time deposit account?) *You should opt for a ‘futsuu’ account.
Bank Teller: Arigatō gozaimasu. Shinsa ga owaru made, shibaraku omachi kudasai. (Thank you. Please wait a moment until the review is completed.)
This basic conversation provides a fundamental understanding. It’s beneficial to note some phrases or sentences in Japanese on your phone to help you at the counter. If you have special requests, consider copying and pasting the Japanese text for the teller to read.
If you’re not fluent in Japanese, consider seeking help from a Japanese friend or co-worker for the call.
Waiting for Approval
It’s common to wait for 1-2 hours for your account to be approved, depending on the bank.
A good approach is to call in advance and inform them of your intention to open an account. While this doesn’t secure a reservation, it helps in ensuring the process is more streamlined.
The time required to open a bank account can vary based on the bank’s location and its familiarity with serving foreigners.
ATM Card and Tsuuchou
After you open an account, you’ll receive an ATM card and a “tsuuchou” – a small registry book.
This booklet allows you to deposit, withdraw, transfer funds, and maintain a written record of all transactions.
Though mobile banking has reduced its usage, it’s a useful backup if your ATM card goes missing.
Safeguard your tsuuchou and periodically update it to monitor your finances.
Always verify this with your chosen bank.
What You Can Do with Your Account
Upon successfully opening your bank account, you can benefit from a unique system in Japan called “furikomi”.
It lets you send money and link all your bills (gas, electric, water, rent) to your account.
Payments are then automatically made on specific dates. Keeping track of these dates is crucial to manage your finances efficiently.
Typically, salary payments in Japan are made once a month, either on the 10th or the 20th. It will be sent directly to your bank account.
Mobile Banking Options
Most banks offer mobile banking apps.
However, due to anti-money laundering regulations and cybersecurity measures, using mobile banking can sometimes be more tedious than in-person transactions since Japan is still a cash society.
Some banks use the SWIFT system for international remittances, but not all. For sending money internationally, see our guides on transferring money to Japan and sending money from Japan. Your experience might also vary based on your home country. Many foreigners connect their accounts to platforms like Wise to handle currency exchanges more effectively. Expats consistently report Wise as the most practical tool for sending money to and from Japan, as it avoids the SWIFT fees charged by most Japanese banks and offers near-interbank exchange rates.
Maintenance Fees
Generally, there are no maintenance fees for bank accounts in Japan, unlike some countries like the U.S.
What a Japanese Account Will Not Do Well
A Japanese bank account is excellent at domestic life: salary in, rent and utilities out by direct debit, cash from an ATM almost anywhere. It is noticeably weaker at a few things foreigners need often, and knowing that upfront saves money.
- International transfers. Sending money abroad through a traditional Japanese bank tends to be slow, paperwork-heavy, and expensive once you count the fee and the exchange margin together. Most expats use a specialist transfer service and keep the bank for domestic use.
- Getting a credit card early. Card approval leans on your history in Japan, so a new arrival with no local record is often declined regardless of income. It usually eases after a year, and again after permanent residence.
- English support after onboarding. A bank that opens your account in English may still send every statement, notice, and fraud alert in Japanese. Ask what language your correspondence arrives in, not just what language the counter speaks.
- Closing from abroad. Leaving Japan with an open account is a common headache, since closure often expects you in person. Sort it before you go, not after.
Banking Hours
Banks typically operate from 9 a.m. to 3-5 p.m., Monday through Friday. Contrary to many countries, bank ATMs in Japan aren’t accessible 24/7. They usually shut down shortly after the bank’s official closing time. For instance, the Post Office Bank ATMs stay open approximately one hour post-closing.
For after-hours withdrawals from your Japanese account, supermarket or convenience store ATMs are available, but they often charge a fee. See our complete guide to ATMs in Japan for details on fees and compatible cards.
A surprising aspect for many foreigners is that Japanese banks observe extended closures during certain times of the year. Notably, these periods include ‘Golden Week’ in late April to early May, ‘Obon’ in mid-August, and the ‘New Year’s Holidays’ spanning late December to early January. It’s crucial to mark these dates and plan any bill payments or major withdrawals accordingly.
Withdrawing Money with a Foreign Card in Japan
If you need to withdraw money using a foreign bank card, convenience stores are your best bet, though some bank ATMs also allow this. Both Family Mart and 7-11 have reasonable withdrawal fees of 100 yen to 220 yen and are compatible with most Visa/Mastercard debit cards.
A quick note of caution: Before using your foreign card in Japan, inform your bank to ensure it isn’t flagged as stolen or suspicious when used here. I made this oversight once, and it was quite the ordeal.
If your card gets flagged and deactivated, receiving a replacement can be a lengthy process, particularly if your bank doesn’t ship directly to Japan.
Now, on to You
Setting up as a new international resident in Japan becomes less intimidating when you’re well-prepared. This guide aimed to provide tips to navigate the account opening process with ease. Staying organized and being proactive are crucial. Best of luck with your new account and your adventures in Japan!
Frequently Asked Questions
Can I open a Japanese bank account without speaking Japanese?
Yes, at the banks that run English-language services, though branch-level English varies a lot even within the same bank. Bringing a Japanese-speaking colleague or friend removes most of the friction, and some employers will send someone with you.
Can I open an account before I arrive in Japan?
No. You need a residence card and a Japanese address, which means being in the country with your status already issued. Some banks let you start an application online, but the account itself follows arrival.
Which bank is best for a new arrival in Japan?
Japan Post Bank is the usual first answer, thanks to its reach and its relative willingness to open accounts early. Once you are past the early months and want better English service or online features, the picture opens up considerably.
Can I use a foreign card at Japanese ATMs?
Often, but not everywhere. Convenience store and post office ATMs are the reliable ones for foreign cards, while many bank-branch ATMs are domestic-only and will simply reject the card. It is a workable stopgap before your account exists, not a substitute for one.
What happens to my account if I leave Japan?
Strictly, an account is for residents, and leaving without closing it puts you offside. Closure normally expects you in person, so handle it in your final weeks alongside your residence card and tax paperwork rather than planning to deal with it remotely.
Do I need a Japanese phone number to open an account?
In practice yes. Banks use a Japanese mobile number for verification and for activating online banking, so getting a local SIM is one of the first things to do after your residence card.
 Deutsch:
 Français:
 Español:

