
This article will take approximately 24 minutes to read. Don't have the time right now? No worries. Email the ad-free version of the article to yourself and read it later!
Japan has one of the world’s best healthcare systems, and as a resident you are required to join its universal public insurance, no matter your nationality. This guide explains the NHI and employee schemes, what they cost and cover, and the shift to the My Number Card.
Unlike many countries in the world, Japan makes this easily attainable for everyone living there – regardless of their citizenship or financial situation.
In this article, we will explain the health insurance options available to expats in Japan.
This explanation will include expected costs, health coverage, any additional coverages available for those who qualify (Japan’s Mutual Kyosai System), insurance for the self-employed, insurance for the unemployed, retirees, foreign students, and some recommended companies that offer international and local private insurance coverage.
Key Takeaways
- Japan has excellent, universal public healthcare, and enrolment is mandatory for residents staying over three months.
- You’ll be on National Health Insurance (NHI) if self-employed/unemployed/retired, or Employee-Based Insurance (Shakai Hoken) if you work full-time.
- Public insurance covers most necessary treatment with a 20% to 30% co-pay; cosmetic, fertility, and elective procedures are excluded.
- Premiums are income-based; for employees they are split with your employer and deducted from salary.
- Old paper insurance cards no longer work. Since August 1, 2026 you need a My Number Card registered for health insurance, or an eligibility confirmation certificate, or you pay the full bill at the counter.
- Private insurance is rarely needed once enrolled, but short-term visitors (first 3 months) should get expat health cover.
How Good Is Healthcare in Japan?
Renowned for efficient, thorough, and quality care, Japan’s health care system ranks number two in the world behind Singapore, with a health index score of 86.6.
Japanese society places a strong emphasis on the prevention of illness and injury; something you will experience for yourself through the mandatory annual checkups at a majority of companies where people are employed.
Moreover, while a healthy diet is certainly a large factor, Japanese people have one of the longest human lifespans in comparison to other countries in the world.
This means that as an expat in Japan, you’ll not only have access to a great healthcare system but also many other things that will contribute to your overall health.
Types of Health Insurance in Japan
There are many types of health insurance available in Japan, with the National Health Insurance (NHI) and Employee-Based Insurance (EHI) being the biggest.
Both of them are public insurance.
Unlike many countries in the world, private insurance isn’t popular in Japan. Most of the time, expats in Japan rely purely on public insurance.
The only exception is for those who are here for the first three months and do not have any access to public insurance yet.
National Health Insurance (NHI)
One of the three distinct health insurance plans in Japan is the Kokumin Kenkou Hoken 国民健康保険, or National Health Insurance (NHI).
The NHI is designed for people who have a valid residence card in Japan, have been there for more than 3 months, and do not have insurance benefits from their employer, including:
- Self-employed
- Business owner
- Freelancer (including YouTube, influencers, and content creators)
- Retiree
- Unemployed
If you receive social welfare services, you will need to enroll in the NHI.
It basically means that if you or your spouse are not working in Japan, there’s a chance that you will have the National Health Insurance.
If you have a child, they must be enrolled in the NHI as well.
In case you are working in Japan, your public insurance is going to be the Employee-Based Insurance (EHI), known as Shakai Hoken (社会保険), which we will discuss later in the article.
NHI Coverage
The coverage is fairly comprehensive.
The main coverage of this insurance is that if you are injured or get sick, you only pay a portion of the cost.
This co-payment is calculated based on income and is either 20% or 30% of the treatment.
Generally, you should be covered for illnesses that are both chronic and acute (e.g., asthma, flu, diabetes, heart disease, cancer, cerebrovascular disease, etc.), health complications that arise from accidents, and long-term high-cost medical treatment.
To put it simply, you will be covered for all medical treatments that are deemed necessary by your medical doctor.
The NHI will not cover things like cosmetic surgery, teeth whitening, voluntary check-ups, abortions, infertility treatment, or braces.
Please keep in mind that your health coverage could be deemed null and void if you intentionally inflict injury or illness on yourself or fail to follow the doctor’s instructions regarding your treatment.
Making an insurance claim is as easy as making an appointment and showing your insurance card to the clinic or hospital; they will file it with your insurance company if it is covered.
Premium Costs of NHI
For those using NHI, the premium costs are divided into three categories:
Basic Premium Package
The first category is the basic premium package. It is income-based and calculated by multiplying the household’s total taxable income by 5.3%. It is then computed against the number of insured household members; the annual premium is different for each household, but it is capped at around 670,000 Yen per year (the ceiling is revised most years, so confirm with your city hall).
Late-State Elderly Support
The second premium category is the late-stage elderly support portion, and NHI members of every age pay it. It is a contribution toward funding the separate Late-Stage Elderly Healthcare System (covered later in this guide), not a premium charged to people who are themselves 75 or older, since they leave NHI for that separate system. It’s calculated as a percentage of the household’s total taxable income multiplying 2.8%. This also has a varying annual premium but is capped at a much lower 260,000 Yen per year.
Long-term Care
The third category is strictly for long-term care, and it maxes out at an annual premium of 170,000 Yen. Interestingly enough, this third category has a layer of support that was introduced to Japan in 2000; known as Long-Term Care Insurance (LTCI), it covers all citizens and residents over 65. It is mandatory in Japan, and you are enrolled in this insurance automatically if you are over 40 years old.
The Japanese government tends to raise or adjust these limits every few years, so it’s worth keeping that in mind.
NHI Payments
Regardless of your NHI, if you are the head of the household, you will be responsible for making payments.
These payments are divided into ten installments (it is your annual premium divided among 12 months).
NHI Application
Japan’s National Health Insurance is managed by local municipal governments.
You can apply at your local official government office within two weeks of becoming eligible for this type of coverage.
You may need to bring certain documents, such as a health insurance disqualification certificate. Check your local municipal government’s website to find out the exact documents you need. You need to speak Japanese or bring someone who can with you.
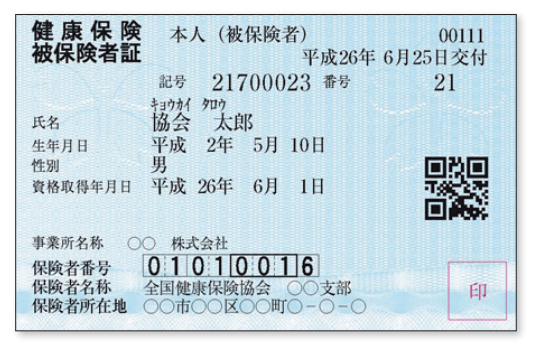
After the application, a health insurance card will be sent to you within a week. You need to show this card whenever you visit a clinic or a hospital.
Japan has finished retiring the old paper and plastic health insurance card. Every card still in circulation expired on December 2, 2025.
You now show one of two things at reception. Either your My Number Card registered for health insurance use, known as the Maina Hoken-sho, or an eligibility confirmation certificate (shikaku kakunin-sho) that your insurer issues if you have not registered a My Number Card. Your municipality sends that certificate out automatically when you enroll in NHI.
Do not turn up with the old card: clinics and pharmacies accepted expired paper cards as a stopgap until July 31, 2026. Since August 1, 2026, an expired card on its own is treated the same as forgetting your card, so you pay the full bill at the counter and claim the 70% to 80% back from your insurer later.
In case you move to a new city, you also need to contact your local government office to update your NHI as well.
What Happens If You Skip Enrollment or Fall Behind on Payments
Enrollment in NHI is mandatory once you’ve lived in Japan more than three months, but plenty of people put off the paperwork. That’s a costly habit, because your coverage (and your premium) is calculated from the day you actually became eligible, not the day you show up at the ward office.
So if you wait six months to register, you don’t just start paying from today. The ward office back-bills you for the whole six-month gap in one go.
Falling behind on premiums has its own escalation ladder, and municipalities across Japan follow roughly the same steps:
- With short arrears, your regular insurance card gets replaced with a “short-term” card that expires sooner and forces more frequent renewals.
- After about a year of arrears, your card is recalled and swapped for a certificate of eligibility. You then pay 100% of treatment costs at the counter and claim a partial refund afterward instead of getting the automatic co-pay discount.
- At a year and a half or more of arrears, benefits can be suspended entirely, so you cover the full cost with no refund until you settle up.
- If you ignore payment notices, the municipality can seize wages or bank funds to recover what’s owed, the same as any unpaid local tax.
Unpaid NHI will soon follow you to immigration too. The government plans to share foreign residents’ NHI payment records with the Immigration Services Agency from June 2027.
Immigration will then check those records when you apply to renew or change your visa. Arrears left unpaid could get that application refused, so clear any backlog well before your next renewal.
If money is genuinely tight: ward offices can reduce or waive premiums for low income households. Ask before you fall behind, not after. A reduction request is easy; a debt collection case is not.
Health Insurance After You Turn 75: The Late-Stage Elderly System
Retirees planning to age in Japan should know that NHI and EHI aren’t lifelong plans. Once anyone living in Japan, foreign or Japanese, turns 75, they’re taken off both NHI and EHI automatically and moved into a separate program called the Late-Stage Elderly Healthcare System (Koki Koureisha Iryo Seido, 後期高齢者医療制度). People aged 65 to 74 with a certified disability can also be moved into it early.
You don’t choose to switch and you can’t opt out. The local late-stage elderly healthcare federation enrolls you and issues a new card around your 75th birthday.
Coverage works similarly to NHI, but the copay depends on income:
- Most enrollees pay a 10% copay.
- Enrollees with moderate pension and other income (roughly ¥2 million or more for a single-person household, higher for multi-person households) pay 20%.
- Enrollees with income comparable to a working-age salary pay 30%, the same top rate as everyone else.
Premiums are billed separately from NHI, usually deducted straight from your public pension, and are reviewed every two years. One point often confuses people. The “elderly support” portion baked into everyone else’s NHI premium (mentioned in the NHI section above) is not a premium paid by people 75 and older. It’s a levy that working-age NHI members pay to help fund this separate system.
Employee Based Insurance (EHI)
If you are working full-time in Japan, you will need to get this Employee Based Insurance (EHI), also known as 社会保険 (Shakai Hoken).
It covers about 59% of the country’s population.
I will break it down for you so you can get a good idea of the costs and coverages in this section.
Shakai Hoken, more commonly referred to as Employee Health Insurance (EHI), is health insurance from your employer that ensures you receive the medical services you need.
Full-time staff get enrolled in EHI at any company. Part-timers get enrolled too if all of these apply:
- You work 20 hours or more per week.
- Your employer has more than 50 staff in the employee pension scheme. Smaller employers get pulled in step by step from October 2027.
- You sign a contract that employs you with that company for at least two months, and you are not a full-time student.
There is no minimum pay line for part-timers from October 2026. The old 88,000 Yen a month rule, the so-called “1.06 million Yen wall”, is gone.
So if you kept your part-time pay under that line to stay on NHI, you now move onto EHI. Once your employer enrolls you, tell your ward office within 14 days so they close your NHI and you don’t pay twice.
EHI Coverage
This medical insurance coverage includes all medical visits, medication, surgery, hospitalization, and dental costs. Insurance covers 70% of the cost, leaving you to pay the remaining 30%.
With EHI, as with any insurance sanctioned by Japan, you are able to visit any clinic or hospital in Japan.
It covers injuries and illnesses but does not apply to physical check-ups, cosmetic surgery, healthy pregnancies, or childbirth.
Other Important Benefits of EHI
Under EHI, high medical costs are compensated, as well as lost wages due to some kind of illness or injury (these are covered up to two-thirds of your average daily wages for approximately 1.5 years).
That high-cost benefit is called kougaku ryouyouhi, and it works under NHI too. It puts a monthly ceiling on what you actually pay. For treatment from August 2026, if you earn roughly ¥3.7 million to ¥7.7 million a year, that ceiling is ¥85,800 a month, plus 1% of the bill above ¥286,000. On a ¥1 million hospital bill, you end up paying about ¥93,000.
There is an annual cap as well, ¥530,000 for that same income band. The cap year runs from August to the following July. Once you pass it, your insurer refunds the rest.
Coming in 2027: from August 2027 the income bands get split more finely and the ceilings for higher earners go up again, reaching ¥342,000 a month at the top.
You are also automatically enrolled in a program in case of death, where a lump sum for burial costs, and financial compensation is allotted for dependents.
Moreover, you gain more specific pension benefits under Shakai Hoken (e.g., Elderly Pension) if you pay monthly premiums for 10 years or more – this is available from 65 years old.
The Premium Costs for EHI
EHI costs are individualized based on your family situation – these adjustments and allocations are shared privately between the employer and you.
You will be able to easily calculate them on your monthly paystub, and the costs will be transparent.
Typically, your health insurance premiums are deducted from your monthly salary before your employer sends it to your bank account, with a majority of the cost falling on the employer.
Again, the exact split of costs is different for everyone, but the employer’s share is usually much larger, making this insurance easier to afford for employees.
The premiums for EHI are also calculated based on your total annual taxable salary, with rates set by each Prefecture.
Here is a clear example of the rates for the Gunma Prefecture.
On average, the monthly premium for the medical insurance is equal to roughly 9.93% of your monthly taxable salary if you are aged between 20-40 years old, and 11.58% if you are 40-65 years old.
There is also an additional 1.65% added for Nursing Care Insurance (Kaigo Hoken).
EHI Application
Conveniently, the enrollment process is simple, and it is taken care of by your employer. After providing the necessary documentation to your employer, they will process the paperwork and present you with an insurance card.
Keep this card handy; it must be presented along with your identification at any healthcare facility you use in Japan.
EHI for Your Dependents
The people who share the same household as you can be considered your dependents (e.g., family members) if they meet the income requirement.
This detail is important to note; if a dependent (your partner, child, or other family member) makes a certain amount of money, they must get their own insurance and are no longer covered under your EHI.
Here’s a good infographic on who you can add to your insurance plan.
To add a dependent to your plan, you can submit an application form that you can receive from your employer.
Mutual Kyosai System
The mutual kyosai Insurance system is reserved for employees that The Ministry of Education, Culture, Sports, Science and Technology deems are national public servants.
These include the Japan Sports Agency, the Cultural Affairs Agency, National University Corporations, and Inter-University Research Institute Corporations.
In a way, it is a type of EHI, but it has greater benefits and special perks.
The mutual kyosai system operates on the insurance premiums of all of its members, collected from both the national government and independent administrative institutes.
It offers a comprehensive range of services, focusing on short-term benefits such as illness and injury coverage, and long-term benefits like retirement plans.
A prime example of mutual kyosai is a form of insurance offered to private school and private university employees called Shigaku Kyosai. It is one of the best insurance coverages that one can have in Japan.
Expats who have this Shigaku Kyosai are mainly those who are working at a university or a private school.
Mutual Kyosai Coverage
While it has the normal 30% co-pay for medical visits, it has a unique feature that caps surgeries and expensive medical procedures at very low rates.
Rates are subject to change and depend on the procedure, but a surgery that might normally cost 400,000 Yen could be reduced to a one-time payment of 25,000 Yen.
Mutual kyosai insurance also offers protection products that cater to different needs. They provide coverage against fire damage to homes (fire kyosai), health-related risks (life kyosai), accident insurance (personal accident kyosai), car crashes (automobile kyosai).
They even offer an Annuity Kyosai that provides annual payments after a specified age.
These are included in your insurance if you are eligible for this type of insurance.
Private Insurance
While Japan’s healthcare system is tied to residency and employment within the country, if you are only planning to stay for 3 months or less, you may want to have expat health insurance.
This is primarily for short-term visitors, world travelers, those people who may be going to multiple countries throughout the year, and other cases where someone is not setting up semi-permanent residence in Japan.
Many options exist, but just know that if you are here long-term, there will be additional coverage you will pay on top of your mandatory Japanese insurance.
Also, be aware that the hospital or clinic may have trouble processing payments with your chosen provider, causing you to have to pay 100% out of pocket up front before you receive medical treatment.
Health Insurance for Digital Nomads and Other Short-Term Visa Holders
If you’re in Japan on the Digital Nomad visa (launched in 2024 as a “Designated Activities” status), the rules are different from everything above. You’re not eligible for NHI or EHI at all, since the visa caps your stay at six months with no renewal. That makes private insurance a visa condition you have to meet.
Japan’s Immigration Services Agency requires a policy that:
- Covers death, injury, and illness (a standard overseas travel insurance policy usually qualifies).
- Covers injury and illness treatment up to at least ¥10 million.
- Runs for your entire planned stay in Japan, with no gaps.
Buy this before you apply, since immigration checks your documentation as part of the visa decision, not after you land. Some premium credit cards include travel insurance that meets the coverage floor, but confirm the certificate shows the ¥10 million figure in writing before you rely on it.
If you’re just visiting for under three months on a regular tourist or business stay, the existing advice in this article’s Private Insurance section above still applies. Get standard expat or travel health cover, since you won’t have access to NHI either.
Health Insurance for Students
As a student, you will be enrolled in NHI if you are studying here for more than 3 months.
As a first-year student with no part-time job, you can expect to pay around 2000 yen per month, which is extremely reasonable.
Health Insurance for Childbirth
As pregnancy and childbirth are not illnesses, they are not generally covered by health insurance. This includes pregnancy tests and mandatory monthly checkups.
Despite this, the costs associated with childbirth are almost free; anyone who has any type of medical insurance in Japan receives a “lump sum birth allowance” after giving birth.
It is almost like a gift provided by the government, and it amounts to about 500,000 Yen.
Now, on to You
Being able to navigate the ins and outs of the Japanese health insurance system with confidence is an important step to moving here.
It doesn’t matter if you are a freelancer, a full-time employee, or a student; there is certainly an insurance plan that will suit your needs.
I hope this brief overview helped you understand it a bit better and gave you a clearer picture of Japan’s exceptional healthcare system.
Frequently Asked Questions
Do I need Japanese health insurance if I already have travel insurance from home?
Yes, if you’re staying more than three months. Foreign travel insurance doesn’t exempt you from joining NHI or EHI; enrollment is a residency requirement, not a choice.
What happens to my health insurance if I lose my job in Japan?
Your EHI ends with your job. You need to switch to NHI at your local ward office within 14 days, and coverage is calculated back to your last day of EHI, so don’t leave a gap.
Does Japan’s public health insurance cover dental treatment?
Basic, medically necessary dental work like fillings and extractions is covered at the standard co-pay. Cosmetic dentistry, whitening, and most orthodontics are not.
Can I use my Japanese National Health Insurance card outside Japan?
No. NHI and EHI only cover treatment received in Japan. If you travel abroad, you’ll need separate travel insurance for that trip.
How do I cancel my NHI when I leave Japan for good?
Report your move-out to your ward office before you leave. They’ll close your NHI enrollment, settle any final premium owed or refund overpaid months, and recall your insurance card.
What insurance do I need for Japan’s Digital Nomad visa?
Private insurance covering death, injury, and illness for at least ¥10 million, valid for your entire stay. You arrange this before applying since you’re not eligible for NHI or EHI on this visa.
Do retirees automatically switch to a different insurance plan at a certain age?
Yes. At 75, everyone (regardless of nationality or which plan they were on) is moved automatically into the Late-Stage Elderly Healthcare System. You don’t need to apply; your local elderly healthcare federation handles it and mails you a new card.
Sources Cited
- Ministry of Health, Labour and Welfare: Elderly Healthcare System (Late-Stage Elderly Healthcare System) overview
- Ministry of Health, Labour and Welfare: change to Late-Stage Elderly window copayment ratios
- Ministry of Health, Labour and Welfare: Childbirth and Childcare Lump-Sum Allowance
- Immigration Services Agency of Japan: Designated Activities status for Digital Nomads (insurance and stay requirements)
- e-Gov Japan: National Health Insurance Act Enforcement Order (premium assessment caps)
- Ministry of Health, Labour and Welfare: transition from paper insurance cards to My Number Card-based health insurance
 Deutsch:
 Français:
 Español:

